Backtesting and quantitative method
A backtest proves nothing until you know how many variants were tried before it. Every article in this section tackles the same question: how to tell a real signal from an artefact produced by the research process itself.
It covers the biases that inflate historical results (data-snooping, look-ahead, survivorship), the validation methods that hold up against them (walk-forward, purged cross-validation), and statistical corrections such as the Deflated Sharpe Ratio.
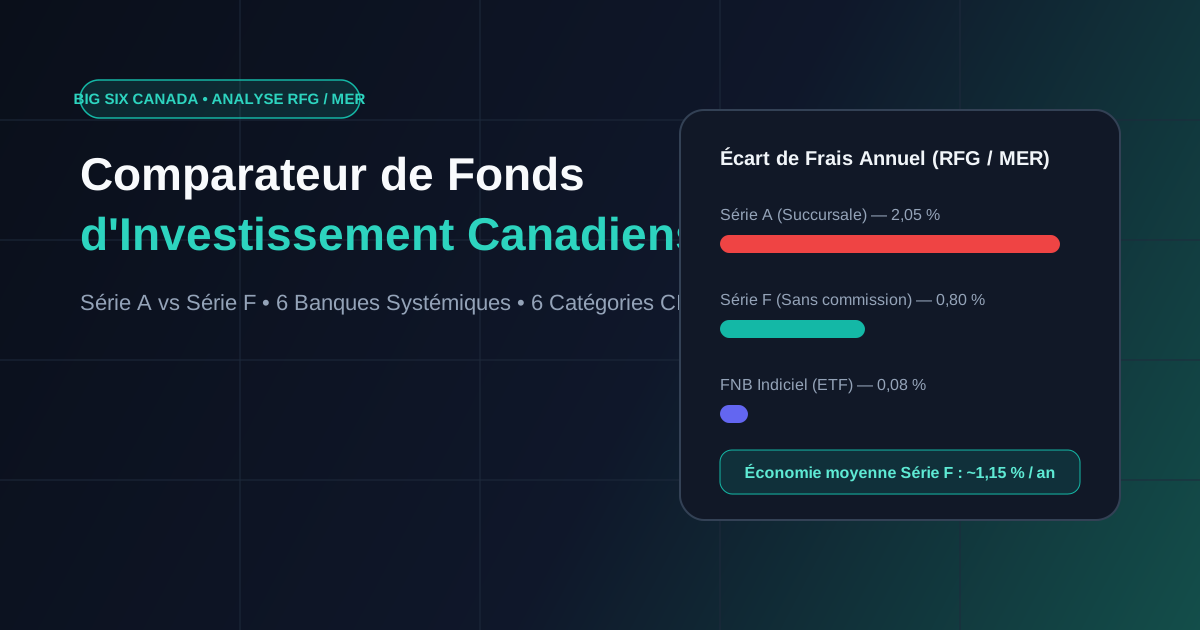
Canadian Investment Funds: How Big Six Bank Management Fees (MER) Silently Drain Your Portfolio (and How to Compare Them)
A 2.05% MER on a retail Series A bank fund erases up to 37.4% of your terminal wealth over 25 years. Explore our Canadian Investment Funds Comparator across the Big Six banks to audit Series A vs. Series F and ETF fees in real time.
Backtesting a Crypto Strategy: The Pitfalls Specific to Digital Asset Markets
A basic bitcoin trend strategy shows 211% a year in a naive backtest, and 41% once corrected. Using real data, we isolated each pitfall behind the gap: look-ahead, fees, funding, exchange choice and parameters.
Why the Sharpe ratio isn't enough to judge a strategy
A high Sharpe can hide a catastrophic drawdown or pure luck from multiple trials. Here are the blind spots of the most-used ratio in quant finance, and how to fill them.

Why Backtest Results Fail in Live Trading: 7 Hidden Pitfalls
Seven concrete, well-documented reasons backtested performance fails to replicate live, from survivorship bias to overfitting, with mitigations for each.
Walk-Forward Analysis vs Cross-Validation for Time Series
Why K-Fold cross-validation leaks future data in trading backtests, and how walk-forward analysis and CPCV provide a valid alternative for time series.

Survivorship Bias in Backtesting: Why It's a Fatal Flaw
Understand how survivorship bias inflates equity backtest returns and how point-in-time data and delisting adjustments fix it.
Modeling Slippage and Commissions in Algorithmic Backtests
Learn why zero-cost fill assumptions inflate backtests and how to model slippage, spread, and commissions realistically in Python.

How to Avoid Overfitting in Algorithmic Trading Strategies
Practical techniques to reduce overfitting in algorithmic trading: temporal splits, parameter reduction, regularization, and heatmap diagnostics.

Best Python Libraries for Backtesting Trading Strategies
A technical comparison of VectorBT, Backtrader, Zipline-Reloaded and QuantConnect/LEAN for Python backtesting, covering architecture, speed and realism trade-offs.
Confirmation Bias in Trading: How It Skews Your Decisions
We tested the chartist rule "after 3 down days, a rebound is likely" on 55 years of Nasdaq data: the market rises less often, not more (49.4% vs 52.2%, p = 0.014). How confirmation bias turns a reversed signal into a conviction.
Portfolio Rebalancing: The 5/25 Rule Explained
Why your allocation drifts over time, and how the 5/25 rule helps decide when to rebalance without overreacting.
Survivorship Bias in Backtesting: Why Your Results Are Probably Too Optimistic
Testing a strategy only on companies and funds still active today artificially inflates performance. Here's how to detect and correct survivorship bias.
Walk-Forward Analysis: Validating a Backtest Without Falling Into Overfitting
Walk-forward analysis reproduces how a strategy would actually be re-optimized over time. Here's how it works and why it detects overfitting better than a simple in-sample/out-of-sample split.
Data-snooping in trading: the beginner quant's #1 trap
Testing 1000 variants then keeping the best guarantees a nice backtest… and a live letdown. Here's how to spot data-snooping and protect yourself with the Deflated Sharpe Ratio.