Confirmation Bias in Trading: How It Skews Your Decisions
We tested the chartist rule "after 3 down days, a rebound is likely" on 55 years of Nasdaq data: the market rises less often, not more (49.4% vs 52.2%, p = 0.014). How confirmation bias turns a reversed signal into a conviction.
Last methodological review:
Quantitative Research · Quant Lab
Backtest & DSR Analyzer
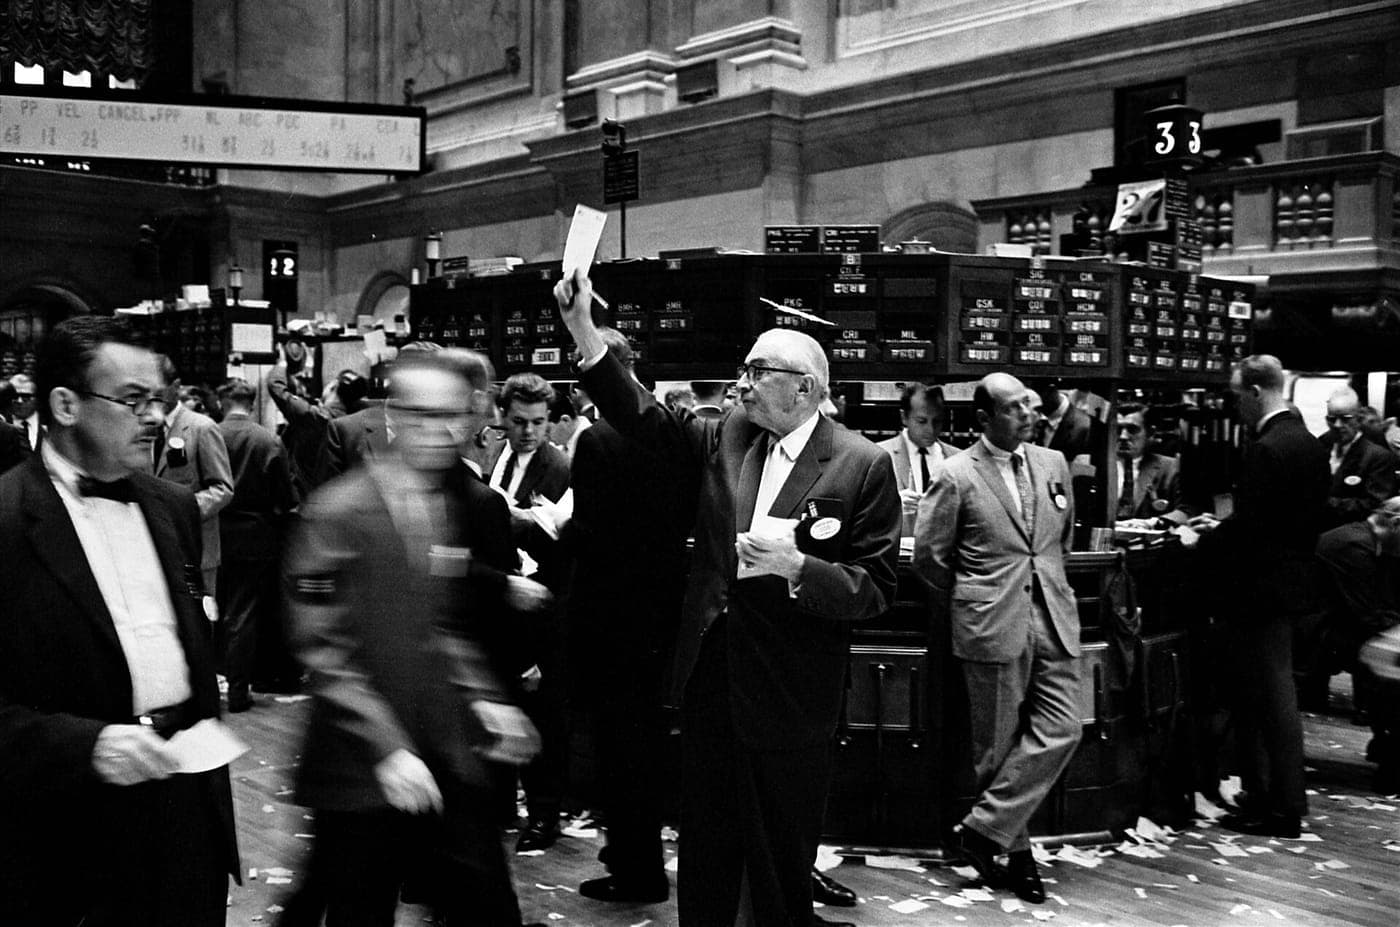
Photo : Thomas J. O'Halloran — Wikimedia Commons (Domaine public)
IN THIS ARTICLE
Key Takeaways (TL;DR)
- Louis) since February 1971, counting every occurrence of three consecutive down days, 1,942 cases over the period, and checking whether the following session was up.
- The brain does not objectively weigh 960 successes against 982 failures: it selectively retains what confirms the pre-existing conviction.
- Our data show that the rebound rate after five consecutive down days drops to 46.5%, versus 52.2% on average: the rule weakens further, yet the trader's conviction only strengthens as the position sinks deeper.
- The good news is that confirmation bias, while impossible to eliminate entirely, can be significantly reduced through structured processes.
"Three down days, a rebound is likely": it is one of the most common reflexes in eyeballed discretionary trading. We tested this rule on 55 years of Nasdaq Composite data (14,511 sessions, 1971-2026): after three consecutive down days, the market rises the next day 49.4% of the time, versus 52.2% on an ordinary day, a statistically significant gap, but in the opposite direction from the belief. This counter-intuitive result is a textbook case for understanding how confirmation bias in trading shapes, and distorts, discretionary traders' convictions.
A chartist rule tested on 55 years of data
The rule tested is simple and widely shared: after three consecutive down sessions, the probability of a rebound the next day would be higher than usual, through a mean-reversion mechanism. We coded this test on daily closes of the Nasdaq Composite (NASDAQCOM series, Federal Reserve Bank of St. Louis) since February 1971, counting every occurrence of three consecutive down days, 1,942 cases over the period, and checking whether the following session was up.
The base rate of daily gains over the whole period is 52.2%. After three consecutive down days, it drops to 49.4% (960 rebounds out of 1,942 occurrences), a gap of 2.8 points against the rebound, with a z-score of -2.46 (p = 0.014, two-sided test). In other words, the "rebound after three down days" rule is not merely wrong: it inverts the actual signal, which leans very slightly toward the decline continuing, not stopping.
Next-day rebound rate after k consecutive down days
Why this result is exactly what confirmation bias looks like
This kind of small but real gap is precisely the favorite playground of confirmation bias in trading. A trader who believes in the rebound rule vividly remembers the times it worked, roughly a coin flip, one rebound out of two, and attributes the failures to "exceptional circumstances" rather than to the rule's lack of statistical grounding. The brain does not objectively weigh 960 successes against 982 failures: it selectively retains what confirms the pre-existing conviction.
From statistical signal to personal conviction
The gap measured here is small, 2.8 points, but it is exactly this kind of marginal gap, neither zero nor spectacular, that lends itself best to biased reinterpretation. A completely absent signal would be quickly abandoned; a massive signal would be hard to deny. It is in the grey zone, a tiny or non-existent edge, that confirmation bias finds the most material to work with, selecting after the fact the cases that suit the original thesis.
The interaction with the sunk-cost fallacy
Confirmation bias never operates alone. It very often combines with the sunk-cost fallacy to form a vicious circle. The longer a position opened on a rule like the rebound rule stays in the red, the more time, energy, and ego the trader has invested in the thesis, and the more receptive he becomes to information that supports it, even marginally, including a simple price bounce unrelated to the original rule.
A concrete example of the spiral
Take a trader who buys after three consecutive down days, convinced of a rebound. If the market keeps falling, he does not question the rule: he tells himself "the rebound is even closer" after four, then five down sessions. Our data show that the rebound rate after five consecutive down days drops to 46.5%, versus 52.2% on average: the rule weakens further, yet the trader's conviction only strengthens as the position sinks deeper.
Number of historical occurrences by k
Concrete debiasing techniques
The good news is that confirmation bias, while impossible to eliminate entirely, can be significantly reduced through structured processes. The first technique is to write an explicit trading thesis before every position is opened, including not only the reasons to believe in it, but above all the precise conditions that would invalidate it, for instance a number of consecutive down days beyond which the position must be cut, regardless of the conviction of the moment.
The post-trade review journal
The second technique is to keep a systematic review journal after every closed trade, whether winning or losing, documenting whether the invalidation conditions defined at the start were respected or ignored. Over time, this journal reveals recurring patterns and makes visible the trader's tendency to ignore certain types of negative signals, exactly like the one observed in our Nasdaq test.
Actively seeking contradiction
The most demanding but most effective technique is to practice a "red team" exercise on one's own thesis: before entering on the basis of a chartist rule, actively test that rule on historical data rather than trusting an impression shaped by a handful of memorable instances. That is exactly the approach followed in this article, and it is reproducible with the backtesting tools available at /tools/backtest-analyzer.
A four-step debiasing process
- 1
Written thesis
Including its invalidation conditions
- 2
Predefined exits
Stop-loss set before entry
- 3
Red team
Write down the best opposing argument
- 4
Post-trade journal
Rules followed or ignored?
Toward a more robust discipline
Confirmation bias in trading is not an isolated character flaw: it is a universal cognitive mechanism, which our 55-year Nasdaq test illustrates with a precise example rather than a generality. Recognizing that a widely shared intuition, the rebound after three down days, can be statistically wrong, even reversed, is the first step; building a decision framework that systematically tests such intuitions before following them is the second. Method: daily closes of the Nasdaq Composite (FRED, NASDAQCOM series), February 1971 to September 2026, two-sided test using the normal approximation. These results do not constitute investment advice.
Frequently asked questions
Can confirmation bias make a trading rule counter-productive?
Yes: in our 55-year Nasdaq test, the rebound-after-three-down-days rule performs worse than average (49.4% vs 52.2%), not better. A trader convinced of the opposite selectively remembers the confirming cases and ignores the 982 failures out of 1,942 occurrences.
How can you tell if a trading rule actually works?
By testing it on a long history and comparing the result to a neutral base rate, using a statistical test (z-score, p-value) rather than an impression. That is the approach applied here on 14,511 Nasdaq sessions, which revealed that the rebound rule performs worse than chance.
Does confirmation bias also affect experienced traders?
Yes, it is a universal cognitive mechanism that experience does not neutralize. The best protection is not seniority but structured processes: a written thesis with invalidation conditions, a post-trade review journal, and systematic statistical testing of rules before following them.
Backtest & DSR Analyzer
Audit Deflated Sharpe Ratio, Monte Carlo distributions, and selection bias directly on your return series.
Analyze a BacktestIndependent financial engineer based in Quebec, Canada, Alain Legrand builds and audits TrueVerdikt's deterministic models: Series A/F mutual fund vs. TSX ETF fee comparisons, RRSP/FHSA tax arbitrage, Canadian mortgage actuarial schedules, and statistical overfitting detection (Deflated Sharpe Ratio & CPCV).
Primary Regulatory & Academic Sources
- OSFI — Guideline B-20 (Residential Mortgage Underwriting) — Residential mortgage underwriting practices, procedures, and minimum qualifying rate stress-test.
- CRA — FHSA, RRSP & Home Buyers' Plan — Official contribution limits ($8,000/yr, $40,000 lifetime FHSA cap), tax deductions, and HBP repayment rules.
- CIFSC — Canadian Investment Funds Standards Committee — Standardized classification of Canadian mutual funds and ETFs used across our MER fee comparator.
- Bailey & López de Prado (2014) — The Deflated Sharpe Ratio — Correcting for Selection Bias, Backtest Overfitting, and Non-Normality. The Journal of Portfolio Management, 40(5), 94–107 (SSRN).
Keep reading
All articles in this section « Quant trading » →
Leveraged NVIDIA ETFs (NVDL, NVDX): Volatility Decay Math and Python Simulation of the -14% Sell-Off
Python Backtesting with Claude (Anthropic): 5 Silent Overfitting Traps and the Deflated Sharpe Ratio